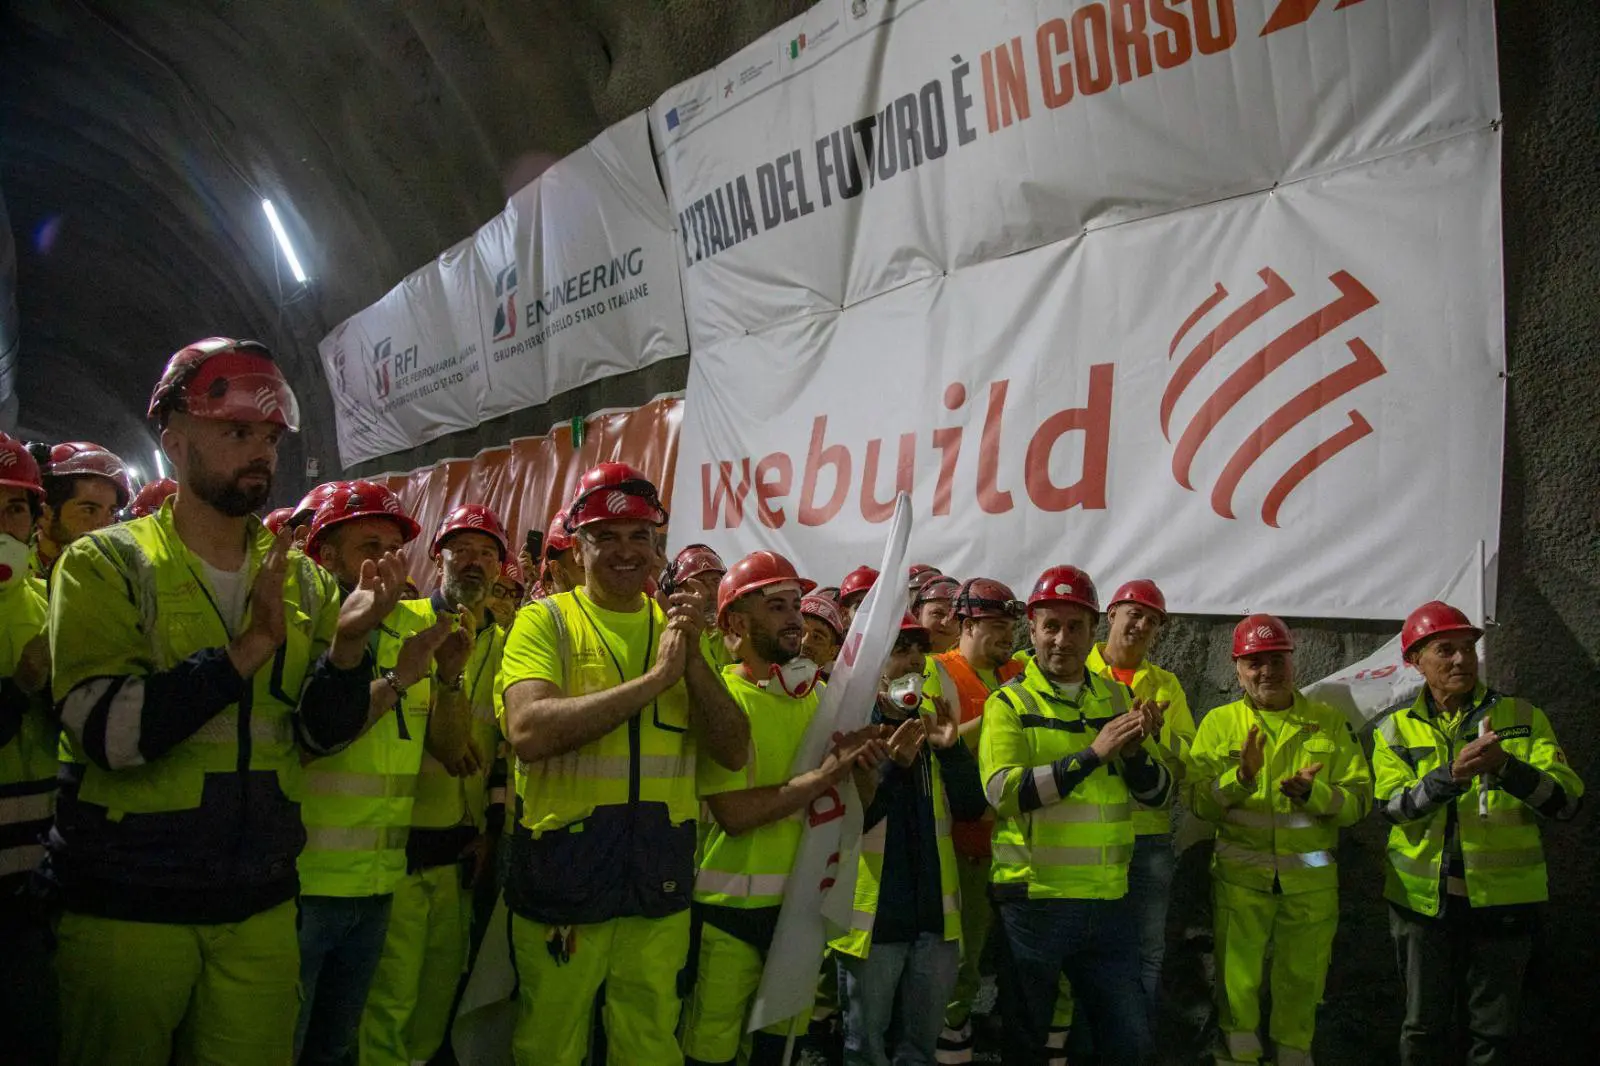
MILAN (ITALPRESS) – The game for the control of Trevi – Industrial Finance, Italian jewel of the underground engineering, undergoes a decisive acceleration. The Consob has given the definitive way to the information prospectus of the voluntary and totalitarian public procurement (OPA) promoted by Webuild.
The proposal of the big works led by Pietro Salini puts on the table a very heavy topic: the cash. The offer includes a cash total of €4.50 per share, enhancing the entire operation around €295 million. Webuild has confirmed in an official note that the offer document will be published in the terms and methods provided by law.
The move of the Supervisory Commission arrives at a crucial moment, on the second day since the official opening of the public exchange offer (Ops) competitor launched by ICOP, the Friuli-Venezia Giulia company of the Petrucco family who moved first to create an integrated pole of the foundations. A temporal overlay that rekindles the spotlight on the very hard clash of governance consumed in recent days. The Board of Directors of Trevi dismissed the ICOP approach unanimously, stating the proposal as non-expensive and free of financial congruence. In its opinion, the board of Trevi disassembled the industrial plant of the ICOP OPS.
First, the management has raised strong doubts about the economic consistency and the real feasibility of operational, commercial and financial synergies announced by the tenderer. According to the leaders of Trevi, the benefits indicated by ICOP would not derive from a real incremental value brought by Friulian society, but from the exploitation of the international platform, the customer network and the technical know-how already consolidated by Trevi.
But it is on the purely financial front that focuses the most severe criticism of the Board of Directors. The structure of the offer of ‘OPS provides exclusively a stock exchange (0,133 ICOP shares for each title Trevi) without any component in cash. An absence that discharges the entire risk of the transaction on the shoulders of the Trevi shareholders. The latter would find themselves in the portfolio titles historically characterized by a reduced float and a lower liquidity on the market, while remaining exposed to the uncertainties of the ICOP industrial plan and the consequent increase of the financial indebtedness of the new aggregate. ICOP’s efficacy conditions also weigh, according to the directors of Trevi, in the exclusive interest of the buyer and freely renounceable, introducing an element of deep uncertainty on the final perimeter of the transaction.
To this is added the spectrum of the clauses of change of control: the change of control could trigger the obligation of early reimbursement of a package of bank loans from 180 million euros in head to Trevi, a burden that would end to burden on the company and, pro share, on the same shareholders who joined the exchange. Also on the plan of the owner and governance the scenario ICOP is judged penalizing.
The shareholders of Trevi would see the status of widespread capital companies disappear to slip into a minority position within a controlled galaxy of law from the Petrucco family through the Cifre holding company. All regulated by a statute armored by derogations on the OPA by consolidation and the mechanism of the majority vote. Finally, the industrial and fiscal alarm: the Trevi leadership reported the total lack of binding commitments by ICOP on employment levels and the protection of foreign offices — a market that generates 80% of the Group’s turnover — combined with ICOP’s intention to assess strategic options on subsidiary Soilmec. A separation of the latter would deprive Trevi of its historical technological integration.
In the background the taxes remain: the stock exchange would force the shareholders to pay taxes on capital gains by drawing on their savings, given the absence of a monetary match in the offer of ICOP.
– Photo press office Webuild –
(ITALPRESS).