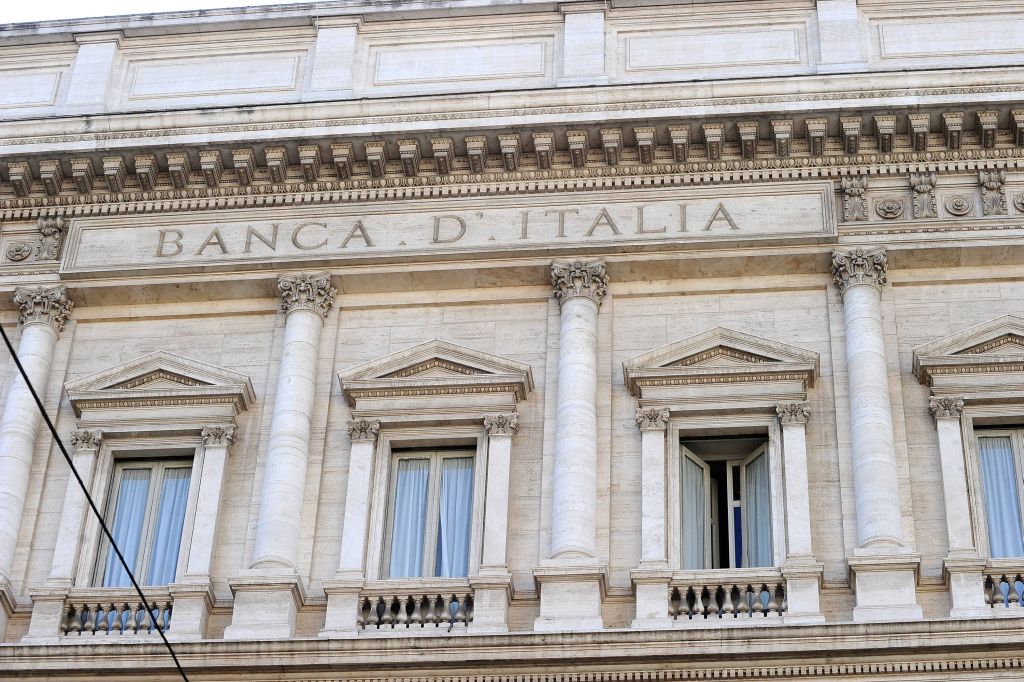
ROMA (ITALPRESS) – “According to the official evaluations contained in the Dpfp last October, in 2027 the net debt would increase, for the first time since 2020, reflecting the impact of the maneuver. The latter increases the deficit of 0.5 points of GDP on average in the next two years and 0.1 points in 2029. From the point of view of the use of resources, the costs of defence and energy are among the greatest voices of maneuver. As already recognised here at the discussion of the Dpfp, major developments in these areas are required by the difficult geopolitical context, in order to reduce strategic dependencies and limit the risks to our economy. The rest of the major resources are mainly used in a plurality of interventions for families, which overall affect the deficit to an appreciable extent. A significant part of expansion has a temporary nature. It is also thanks to their coming less than in 2029 net debt would return under 3%.” Thus the head of the Economics and Statistics department of the Bank of Italy, Andrea Brandolini, in audition on the maneuver.
“As a whole, we estimate that the budget law increases the available income of households, even if in a limited way, and to a slightly greater extent for families with average-low income. At the same time, it increases the complexity of the physical taxation regime: it reduces the taxable basis of Irpef and increases the number of rates. It also introduces additional differentiated schemes. A less complex system would make it easier to increase its efficiency. For taxpayers, it would encourage the planning of business choices, consumption and investment,” he added.
“The prudence in the management of public accounts and the desire to respect the new framework of European rules have been appreciated both by investors, with a reduction of the differential of return between the Italian and German government bonds, both by rating agencies, and in 2025 have reviewed the assessment of the credit merit of the Italian State. The discretionary increase in deficit, however transitory, is expensive, especially for an economy with a high debt and in a context of high interest rates such as the present. In a medium-long term perspective, it is beneficial to focus resources on measures that contribute to increasing the growth potential of the economy,” he said.
“The draft budget law again intervenes on the discipline of financial transaction tax. In particular, a doubling of the rates is envisaged, which follows the one laid down by last year’s manoeuvre. Overall, the share purchase rate and other participatory financial instruments would range from 0.2% to 0.8; from 0.1 to 0.4 in the case of company instruments with capitalization equal to or greater than 500 million, and negotiations on regulated markets or multilateral systems. Similarly, the rate applicable to high frequency operations would also double further, from 0.02 in force in 2025 to 0.08 from 2027. The new measures would determine a greater permanent revenue of 1.4 billion per year,” he said.
“With the measure of the bill, the rate applied to transactions on regulated markets would reach the French one, would be double the Spanish one, would remain less than the ordinary rate applied in the UK. Germany and the Netherlands do not generally apply an FTT to equity transactions. For operations outside the regulated markets, the Italian rate would be higher than the ordinary rates applied in the countries considered. In highly integrated global financial markets – Brandolini concludes – the repercussions that the increase in tax could have on the liquidity of the domestic market must be carefully assessed.”.
– photo IPA Agency –
(ITALPRESS).